by Jodie | Jan 17, 2017 | In The Media
Gold Coast-based advice firm Wealth Planning Partners has launched a subsidiary firm that will focus specifically on Australia’s growing ageing population.
Advisers Therese Jarrett and Amanda Cassar will head the subsidiary Trusted Aged Care Services, according to a statement.
Ms Jarrett said she has become increasingly busy in keeping up with demand, having specifically focused on aged care advice for around four years.
“We shared a mutual interest in the aged care arena based on our personal family needs and brainstormed ideas on how we could make the transition easier for both those needing care and their families,” Ms Jarrett said.
Ms Cassar further added that it was important to be ready for the opportunity and be equipped to deal with the transition process.
“To that end, we have both completed the Aged Care Steps course to become Accredited Aged Care Professionals and will offer varying services depending on the needs of the client,” Ms Cassar said.
We already have a relationship with a number of facilities, but are keen to visit more homes and have a greater understanding of what each offers to better assist our clients into a facility that suits them best.
“We also stay in touch for up to three months after entry to ensure all goes well.”
Wealth Planning Partners is a corporate authorised rep of Financial Services Partners.
VISIT WEBSITE

by Jodie | Jan 13, 2017 | In The Media
Financial Standard
A Queensland financial advice practice is launching a subsidiary business assisting the elderly transition into aged care.
VISIT WEBSITE
by Jodie | Jan 3, 2017 | In The Media
As you’re probably aware, when you donate to registered charitable organisation, your gifts are a tax deductible donation that can boost your tax refund or reduce the amount of tax you pay… completely aside from the feel good factor you get of supporting those less fortunate.
Most charities exist solely to support a good cause and rely exclusively on donations to continue their work. According to the Charity Donations Guide by Choice (September 2014) nine out of 10 Australians give to charity each year.
Here’s a short set of tips to making your gift go further and claiming your donation back at tax time.
What are some ways to give?
For those who aren’t always flush with funds, Choice advises that one way to give that is gaining in popularity is to volunteer. Some donate goods that can be used or sold. Others who are able, are happy to give directly to collection agents or donate directly via websites.
More than 30% of Australia’s population volunteer with not-for-profit organisations, providing an average of 56 hours labour each on an annual basis, a boon for cash strapped charitable organisations. If you are interested in volunteering some of your time, you can visit the Go Volunteer website to learn about opportunities available close to you, or even offshore, whatever is your preference.
Alternate ways to give are charity are by hosting high teas, dinners and balls. Just keep an eye on costs though as the price of the venue and catering can eat into your donation. In a small way, purchasing merchandise on an annual event day also adds to the bottom line of many organisations.
Tips for claiming charitable donations
Charitable donations are generally tax-deductible but before claiming any donations on your tax return, here are a few tips:
- The charity must be classified as a deductible gift recipient (DGR.) To check, visit the Australian Business Register. (Most charities are happy to let you know their status.)
- To qualify for a tax refund, your gift must be greater than $2. Keep receipts for any donations you make.
- The gift must truly be a gift – a voluntary transfer of money where you receive no benefit or advantage. You cannot claim items such as raffle tickets, pens, merchandise, chocolateor membership fees.
Many businesses try to find a charity that aligns with their business for maximum leverage. Businesses who offer goods and services for children find charities that benefit youth. Those supporting women might choose female cancer or domestic violence organisations. Those in finance may support poverty alleviation or micro-finance groups offering opportunities in third world countries. If you resonate strongly with the cause you support, you’ll feel much more aligned to the outcomes.
Another area worth considering, is how many cents in every dollar actually go to where they’re needed. Some charities are extremely admin heavy and over half of funds donated (or more) go to head office staff (or the CEO’s lear jet) rather than those we believe we’re supporting. It’s worth doing the research to find out exactly what goes where and most are very transparent now about this and the information can be found from a quick internet search.
A lot of larger organisations now are incorporating Corporate Social Responsibility programs within their businesses and finding both their staff and clients are loving the involvement.
Two favourite charities that Wealth Planning Partners are proud to support financially, and with our time, are The Hunger Project, who aim to eradicate chronic, persistent hunger by 2030 (with 81c in the dollar going where required) and Hands Across the Water, helping orphaned and disadvantaged children in Thailand (with 100% of funds utilised by the charity.) And, outside of giving ‘just money’ our Director has travelled to Uganda, Malawi and Thailand to see the funds in action and be personally connected with the benefits. This in turn raises profile and clients and colleagues alike are interested in the stories and leadership lessons learned along the way.
Have a think today about whether or not you’d like to include philanthropy in your business or personal plans… and how best to go about it.
VISIT WEBSITE
by Jodie | Dec 20, 2016 | Australian Economy, Debt Management, Finances, Wealth
Apparently, among richer nations, Aussies households are among the most in debt.
Research from LF Economics, using official data, shows that Australian household debt has risen to 123% of the nation’s economic output, pushing both Denmark and Switzerland into second and third place respectively. According to the Reserve Bank, household debt-to-income ratio reached a record 186% in 2015.
The housing boom is most often to blame forcing many buyers into large mortgages. But don’t stress just yet, it’s not all bad news.
Debt isn’t always a bad thing. Chances are by now you’ve heard of ‘good’ and ‘bad’ debt.
Good debt is usually used to produce an income and create wealth, whereas bad debt reduces our worth.
Utilising debt to purchase an investment property or share portfolio is usually seen as ‘good debt.’ Property value are expected to rise of the long term, and you receive an income in the form of rent. Shares are also expected to go up and dividends are often received along the way. Interest expenses are usually tax deductible and can often be claimed against income.
But don’t forget, investments and markets go up and down! Seek appropriate advice and consider your circumstances.
Bad debt is borrowed to buy goods that depreciate in value, don’t produce an income and usually aren’t tax deductible. The new car, jet ski, motorbike, caravan or loans for holidays are all included.
If things are getting out of hand for you and it’s time to start getting on top of your finances again, star first with your non-deductible debt and the one with the highest interest rate. It may feel good to lose the smallest credit card first, but you’re better off not paying the additional interest the other one is incurring.
Most people set goals for the new year that include getting on top of their finances in some way. I’d suggest you pick just one goal that you’re committed to and stick to it. Pay off that one annoying credit card in the coming 12 months, lose that personal loan or consolidate those super funds. Whatever is your biggest bug bear, I hope you get through it in 2017.
by Jodie | Nov 10, 2016 | Australian Economy, Debt Management, Self Managed Superannuation Funds
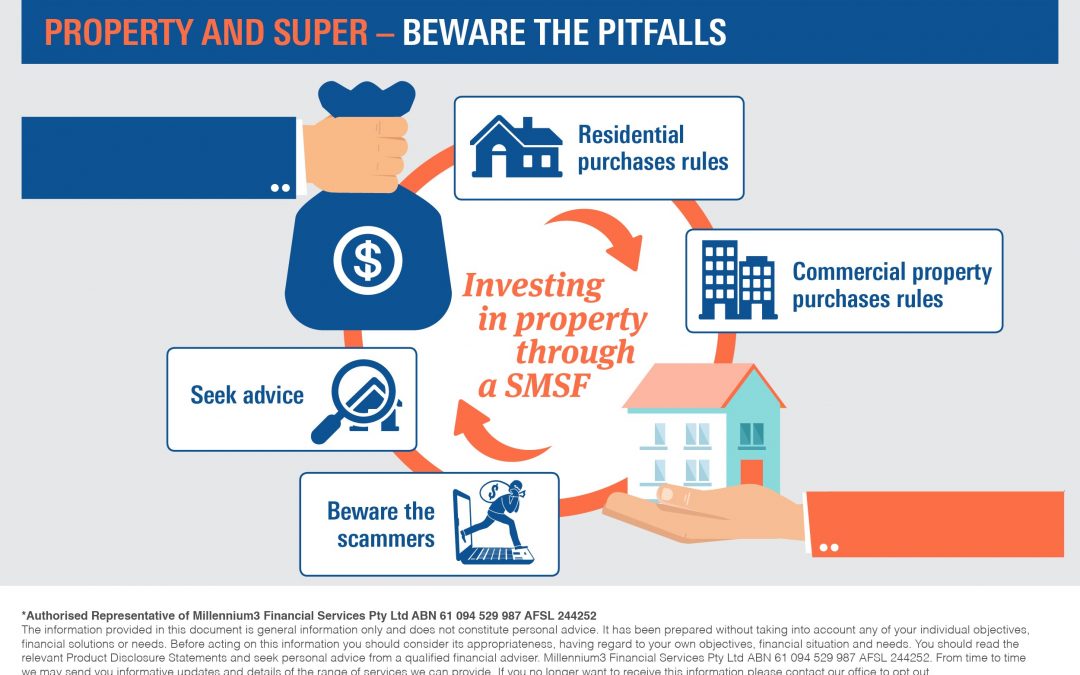
Recent years have seen a rush of investors buying property through super. But while the strategy has its advantages, there are also some potential risks to be aware of.
The pitfalls
While property has been a good performer in recent years, property investing still involves a number of risks.
Some hidden costs in owning direct property can catch buyers unaware, such as building maintenance costs and or levies. A property’s rental income may also not be sufficient to cover your mortgage payments or expenses, and what would happen if your property was vacant? Do you have enough disposable income to cover the costs yourself? And while interest rates are currently at record lows, an eventual switch in interest rate policy would lead to higher repayments.
In addition, past performance is not indicator of future performance so there are no guarantees your property will increase in value. You should also weigh up the impact of notoriously high entry and exit costs such as stamp duties, legal fees, agent’s fees and advertising costs on your investment.
One of the most important principles of investing is the benefits of diversification. So, if you invest the entirety or a large part of your SMSF in property you will have all or most of your wealth concentrated in the property market, leaving you highly exposed to a market downturn.
The pros versus the regulations
Investing in direct property, whether residential or commercial, can provide diversification benefits for a portfolio that may otherwise be dominated by listed shares, and offers the potential benefit of rental income and the opportunity for capital growth.
However, investing in property inside SMSFs is highly technical in terms of regulations and potential tax implications. In particular, there are strict rules around purchasing property through an SMSF specific to buying and or renting to “related” parties. As such, it’s prudent to seek professional advice on this area.
Commercial property
The strategy of using your SMSF to buy commercial property to lease back through their business is again subject to strict regulations and if you are thinking of replicating this you should discuss the regulatory requirements with your adviser.
According to the ATO, you can invest in commercial property, including your own business premises, through your SMSF, however the overall fund must still meet the sole-purpose test of providing retirement benefits to its members. When dealing with commercial property, an SMSF can generally buy the property and lease it back to a member or a related party of the fund – including the member’s business. Another regulatory hurdle to be particularly aware of includes having an arm’s length sale price and lease arrangement for the property in question when acquiring and or leasing the property to a member or related party of the fund.
Beware the Scammers
Unfortunately there have been instances of scammers operating in Australia using tactics such as:
• persuading people to access their super early to buy property;
• seminars where salespeople use pressure selling tactics to encourage you to make quick decisions; and
• cold calling from companies offering free financial advice or unreasonable returns on properties which are often located overseas.
What next?
Bricks and mortar can be a great long-term investment and may help to set you up well for retirement, but any such plan should be considered in the context of your overall financial plan and discussed at length with a trusted financial adviser. In addition, it is also prudent to do your own research by visiting the Australian Taxation Office’s webpage on self managed super funds.
Pros and cons of investing in property, Moneysmart.gov.au at: https://www.moneysmart.gov.au/investing/property#investment
Superannuation Industry (Supervision) 1993 Act and refer to a summary at the ATO website: https://www.ato.gov.au/super/self-managed-super-funds/investing/sole-purpose-test/
https://www.ato.gov.au/Super/Self-managed-super-funds/In-detail/SMSF-resources/Valuation-guidelines-for-self-managed-super-funds/?page=10